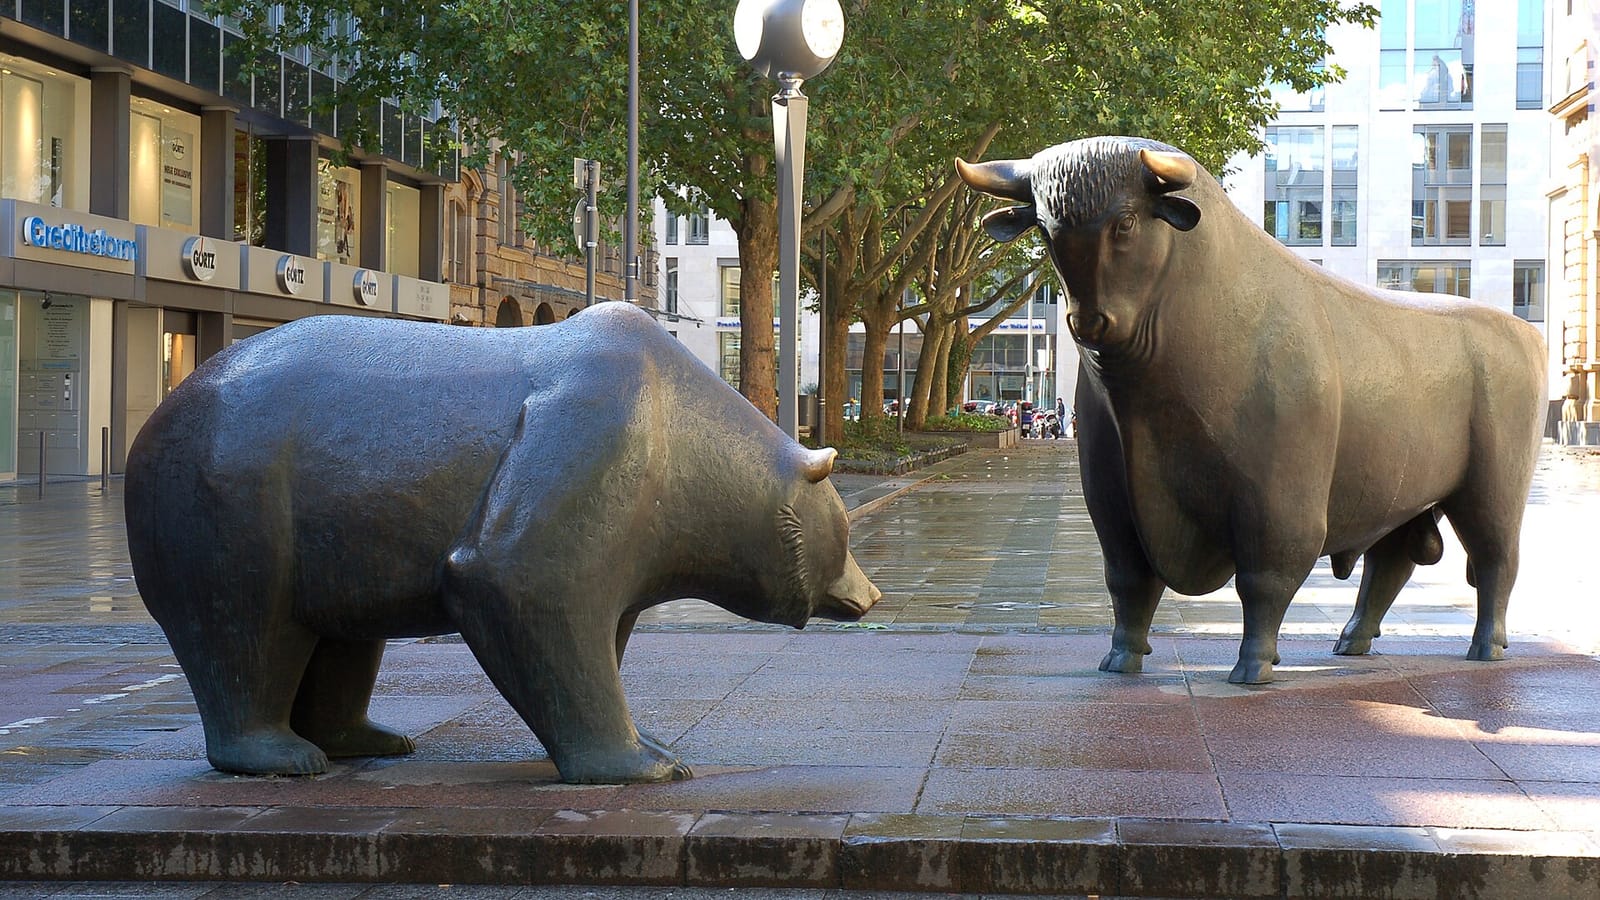
When you invest for the long term, the returns you ultimately achieve depend on more than just picking the right funds. They depend on whether you can stick to your plan when markets fall. This is where risk tolerance comes in. It is not a measure of how much money you have, but a measure of how much short-term discomfort you can endure without making a decision you will regret. This guide explains what risk tolerance is, how it differs from your financial ability to take risk, and how to assess yours using a simple, first-principles approach.
What Is Risk Tolerance?
Risk tolerance is your emotional comfort with volatility and short-term losses in pursuit of long-term gains. It is a personal, psychological trait, not a financial one. Two investors with identical savings and incomes can have completely different risk tolerances: one may sleep soundly holding a portfolio that drops 30% in a bear market, while the other may feel anxious with a 10% dip.
Investors are commonly classified into three broad profiles. Aggressive investors prioritise capital appreciation and accept large short-term declines in exchange for higher expected long-term returns. Moderate investors seek a balance between growth and stability, often accepting some volatility in exchange for smoother returns. Conservative investors prioritise preserving capital and accept little to no volatility, even if it means lower long-term growth.
| Profile | Typical Equity Allocation | Primary Goal |
|---|---|---|
| Aggressive | 80–100% | Capital appreciation |
| Moderate | 40–70% | Growth with some stability |
| Conservative | 0–30% | Capital preservation |
Risk Tolerance vs. Risk Capacity
It is easy to confuse risk tolerance with risk capacity, but they are distinct concepts. Risk tolerance is your willingness to take risk. Risk capacity is your financial ability to absorb losses without derailing your goals. A young professional with stable earnings and no dependents may have a high risk capacity even if they feel nervous about volatility. Conversely, a retiree who needs to withdraw from their portfolio next year has a low risk capacity regardless of how calm they feel during a market dip.
A high tolerance does not mean high capacity when money is needed within a few years. If you plan to buy a house in two years, that money should not be exposed to the same volatility as your retirement savings, even if you personally feel comfortable with the risk.
The Drawdown Formula for Equity Exposure
A practical way to estimate a sensible equity allocation is to use a drawdown formula. A drawdown is the decline from a historical peak in a variable such as cumulative profit. The Maximum Drawdown is the worst peak-to-valley loss since an investment's inception. A generally accepted measure of a bear market is a price decline of 20% or more over at least a two-month period. A decline of 10% to 20% is classified as a correction.
The formula is: monthly net income multiplied by your risk comfort period, divided by the expected market drawdown percentage. The result gives you an estimate of the maximum amount you should keep in equities, expressed as a number of months of income.
For example, if your monthly net income is €2,000, your risk comfort period is 12 months, and you expect a bear market drawdown of 30%, the calculation is: (€2,000 × 12) ÷ 0.30 = €80,000. If your total investable assets are €80,000, this suggests an equity allocation of roughly 100%. If your assets are €40,000, the formula suggests you should not allocate more than €80,000 to equities, leaving the remainder in less volatile assets.
This formula acts as a sanity check. It anchors your allocation to a concrete financial reality rather than a gut feeling that may change when markets fall.
Factors That Raise or Lower Your Tolerance
Several factors influence both your actual risk tolerance and the level of risk you should practically consider. Your investment horizon is perhaps the most important: the longer you can leave money invested, the more volatility you can afford to absorb because markets have historically recovered from downturns over time. Income stability also matters. Someone with a secure, predictable income can tolerate more risk than a freelancer with variable earnings. Dependents, including children or elderly parents you support, reduce your capacity to take risk because you need reliable funds in the near term.
Other assets you hold raise your effective tolerance. A paid-off home, a pension, Social Security or a stable inheritance all provide a financial buffer, meaning you can take greater risk with your investable assets. Portfolio size matters too: a large portfolio relative to your spending needs can absorb a significant drawdown without forcing you to sell at a loss.
The Psychology of Risk: Loss Aversion and Overestimation
Understanding the psychology of risk is essential because most people overestimate their true tolerance. Loss aversion, first proposed by Amos Tversky and Daniel Kahneman in their 1979 prospect theory, is the cognitive bias in which losses tend to be treated as if they were twice as large as an equivalent gain. In a classic example, a person choosing between a guaranteed €50 and a coin flip paying €100 or nothing (expected value €50) is risk averse if they would accept a certain payment of less than €50, such as €40, rather than take the gamble.
This bias has a direct impact on investing. In a calm market, you might confidently tell a questionnaire that you are an aggressive investor. But when a real downturn hits and your portfolio drops 20%, the pain of the loss feels far larger than the earlier thrill of gains. This is why many investors panic-sell at the bottom. The questionnaire measures your stated tolerance; a real bear market reveals your actual tolerance.
The Cost of Mismatch
A mismatch between your portfolio's risk and your true tolerance is costly in two opposite directions. If your portfolio is riskier than your tolerance, a sharp market decline will trigger emotional distress and likely lead to impulsive selling at lows. This crystallises losses and prevents you from benefiting when the market recovers.
On the other hand, if your portfolio is more conservative than your tolerance, you may avoid the anxiety of downturns but expose yourself to a different risk: the erosion of purchasing power. Inflation steadily reduces the value of cash and low-yielding assets over time. A conservative portfolio that returns 2% annually in an environment with 3% inflation is effectively losing money in real terms. Excessive conservatism can be just as damaging as excessive risk-taking over a long investment horizon.
Reassessing Tolerance Over Time
Risk tolerance is not fixed. It should be reassessed after major life events such as marriage, having children, changing jobs, or approaching retirement. A prolonged market stress period can also reveal new information about your true tolerance. After a significant downturn, ask yourself honestly whether you would have sold or held.
Questionnaires are a useful starting point, but they work best when combined with a review of historical returns. Looking at how a balanced portfolio behaved during past bear markets can help you calibrate your expectations. A moderate portfolio, often structured as a 50/50 or 60/40 mix of stocks and bonds, has experienced significant declines but has historically recovered over multi-year periods.
A simple process for reassessment can be visualised as a flow:
Key takeaways
- Risk tolerance is your emotional comfort with volatility; it is distinct from your financial ability to take risk, which is your risk capacity.
- Use the drawdown formula as a sanity check: monthly net income multiplied by your risk comfort period, divided by the expected drawdown percentage, gives a concrete anchor for your equity allocation.
- Loss aversion means you will likely overestimate your tolerance until a real downturn tests it; design your portfolio for the market conditions you fear, not the ones you hope for.
- A mismatch is costly: a portfolio too risky for you leads to panic selling at lows, while a portfolio too conservative erodes your purchasing power through inflation.
- Reassess your tolerance periodically, especially after major life changes or prolonged market stress, and use historical return reviews to ground your expectations in reality.
- Aligning your allocation with your actual tolerance, not your aspirational tolerance, is the foundation of a portfolio you can stay invested in through market cycles.
Educational only — not personalised investment advice.